Buying your first home feels entertaining good up until eventually the documents starts stacking up. Somewhere between the inspection report, escrow timeline, loan disclosures, and shifting containers, dwelling house insurance coverage stops sounding non-compulsory and starts offevolved sounding very actual. For many first-time home owners, that may be the moment the questions commence. What does a wellknown policy correctly canopy? How much insurance plan do you desire? Why does one quote look economical and an alternate sense especially prime?
The short reply is that domicile insurance plan protects a long way greater than the development itself. It can assistance pay to restore your property after protected spoil, update confidential assets, cowl legal responsibility if someone receives harm on your private home, and pay brief dwelling charges if a extreme declare forces you out of the condo for ages. The longer answer is in which americans quite often get tripped up, in view that not all guidelines are equipped the similar, and now not every risk is covered immediately.
If you are acquiring in El Monte, these details count number even greater than they will look at first glance. A home owner near Santa Anita Avenue may perhaps face numerous useful matters than somebody in the direction of North El Monte, Mountain View, or the areas round Valley Boulevard and Peck Road. Older homes can deliver wiring or plumbing questions. Recently up to date residences could qualify for more effective phrases. Proximity to busy roads, mature trees, and native flood-services locations may also form your coverage strategies. Even standard realities, like how simply a contractor can reply after a hurricane or plumbing leak, have an impact on what “right insurance” genuinely skill in exercise.
What domicile assurance truely does for a primary-time buyer
A lot of new owners imagine home insurance is particularly approximately fires and primary disasters. It does canopy big losses, however the daily cost probably shows up in smaller, more general claims. A burst delivery line less than a sink. A kitchen grease hearth that spreads smoke through 1/2 the apartment. Wind lifting shingles off the roof. A guest slipping on wet entrance steps. These usually are not dramatic motion picture scenes, however they are the sorts of losses that turn a attainable month right into a economic mess if you are uninsured or underinsured.
The coverage you buy is really a package of protections. One element covers the living, that means the physical constitution of the area. Another covers different platforms, corresponding to a detached storage, fence, or shed. Personal belongings covers your property, from furniture to garments to electronics, concern to policy limits and one-of-a-kind sub-limits for convinced classes. Liability policy supports whenever you are legally answerable for injury or assets damage. Loss of use insurance policy can guide with resort debts, foods, and related quotes in case you can not accurately stay in the abode after a blanketed experience.
That sounds practical ample, but the issues starts when purchasers count on each coverage handles every event the similar way. They do not. Water smash is a superb example. Sudden and unintentional water wreck from a burst pipe is in the main lined. Slow leaks owing to overlook recurrently are usually not. Flooding from exterior water is commonly no longer incorporated in a favourite domestic assurance coverage. Earthquake wreck traditionally requires separate policy as properly. If you're a primary-time client near the San Gabriel River hall or in low-lying wallet around El Monte wherein heavy rain can create drainage worries, that contrast subjects extra than so much other people become aware of.
The big difference between industry magnitude and rebuild cost
One of the maximum general mistakes I see amongst first-time householders is confusing the value of the apartment with the money to insure it. Those don't seem to be the related wide variety.
Your home’s marketplace significance comprises the land, region call for, college patterns, and local gross sales recreation. Insurance is focused on reconstruction price, which means what it is going to possible check to rebuild the house with similar parts and labor after a total loss. In some ingredients of El Monte, extraordinarily wherein houses fluctuate in age and transforming pleasant, rebuild charge can fluctuate meaningfully from purchase rate. A modest-seeking domicile with up-to-date electric, custom cabinetry, and a tile roof can money more to rebuild than a patron expects. On the turn aspect, a dwelling bought at a top class attributable to position close Whittier Narrows or commuter get admission to may not desire house insurance policy equivalent to the full sale expense.
That is why a fine abode insurance agent will ask specific questions about sq. photos, roof age, creation style, enhancements, and hooked up platforms other than simply plugging inside the sale expense and relocating on. This is one region where experienced pros earn their hinder. A purchaser-concentrated enterprise routinely spends time ensuring the living quantity reflects life like alternative necessities, now not guesswork.
What a regularly occurring coverage aas a rule covers, and wherein persons get surprised
A popular homeowners coverage in many instances covers the house for exact named hazards or, in many situations, broader “open peril” insurance plan for the architecture based at the model. That language subjects, yet what topics greater to maximum purchasers is knowing the gaps.
People are incessantly surprised to learn that jewelry, tremendous art, firearms, industry belongings, and collectibles may have constrained assurance except separately scheduled. They also are shocked that domicile-based industrial publicity can complicate matters. If you run a aspect industry out of the garage, save inventory at home, or have valued clientele in certain cases stop through, you will desire endorsements or even separate industrial assurance or business insurance toughen. A policy designed for standard residential use will never be equipped to take up every commercial-same menace.
The identical goes for sure liability cases. If your dog has a background of biting, if you very own a trampoline, or for those who hire out component of the belongings, your insurance communication wishes to get more exclusive. First-time people today are continuously centred on last prices, no longer part situations. But aspect cases are precisely wherein luxurious claim disputes tend to turn up.
A https://franciscosiwh810.swiftnestly.com/posts/committed-to-excellence-what-great-home-insurance-service-looks-like sensible way to place confidence in insurance plan is this:
- Your policy may want to in shape how the house is if truth be told used, not simply how it seemed on remaining day. Water, earthquake, and flood dangers deserve separate recognition as a result of they are known sources of bewilderment. Personal property limits are generally ok for a few families and far too low for others. Liability insurance policy is customarily less costly to enlarge when put next with the check of a extreme lawsuit. Bundling home insurance plan with automobile coverage can from time to time advance cost, but the have compatibility of the policy nevertheless matters more than the discount.
That closing level is value lingering on. Many first-time patrons additionally need automobile coverage, and bundling with the same provider can make experience. If you're already purchasing for vehicle assurance sellers near me, motor vehicle insurance coverage near me, or an automobile insurance plan agent near me, ask how the package deal differences deductibles, billing, and claim managing. The most excellent bundle just isn't at all times the bottom headline price. It is the single that supplies you strong defense throughout equally dwelling insurance coverage and auto assurance without leaving weird and wonderful gaps between insurance policies.
Deductibles, and why low-cost premiums can backfire
A deductible is the volume you pay out of pocket earlier your insurance plan kicks in on a coated estate claim. Higher deductibles sometimes cut back your top rate. Lower deductibles most likely lift it. Straightforward satisfactory, however here's where investors normally retailer themselves into a bad decision.
A very prime deductible can make per thirty days payments suppose more viable, quite correct after a down payment and transferring bills. But if a declare happens six months later, that discount may well think painful. A first-time property owner who chooses a $five,000 deductible to save a modest volume every month may possibly feel sorry about it whilst a roof leak ends up in indoors ruin and speedy out-of-pocket bills.
The more effective question isn't “What is the most cost-effective deductible conceivable?” It is “What amount may just I realistically tackle with out derailing my funds?” If the solution is $1,500 or $2,500, construct round that. Insurance deserve to switch severe menace, not create a second economic emergency if you want to apply it.
Why your quote can trade from one employer to the next
Two insurers can check out the identical condo and provide exceedingly completely different prices. That does now not routinely imply one is overpriced. It traditionally skill they weigh risk in another way.
The business enterprise is perhaps hunting at declare heritage inside the zone, the age of the roof, distance to hearth maintenance, sort of wiring, previous losses linked to the belongings, the circumstance of plumbing structures, or whether or not the house has shielding gadgets like important alarms and water leak sensors. Some carriers are surprisingly cautious with older properties. Others are extra comfy with them if updates are documented. One provider could favor bundled consumers who additionally vicinity automobile coverage or existence insurance plan with the identical organisation.
That is one cause many customers start off with searches like coverage dealers close to me, home coverage agent, automobile insurance agent, or auto insurance dealers and then compare conversations, no longer simply expenses. A responsible service adventure matters. You favor anyone who explains endorsements in simple English, returns calls, and allows you remember what's replacing from quote to cite.
Marvin Martinez: Allstate Insurance El Monte
For owners in El Monte who desire local assistance, one possibility is:
Marvin Martinez: Allstate Insurance
3580 Santa Anita Ave # J, El Monte, CA 91731, United States +1 626-877-0600 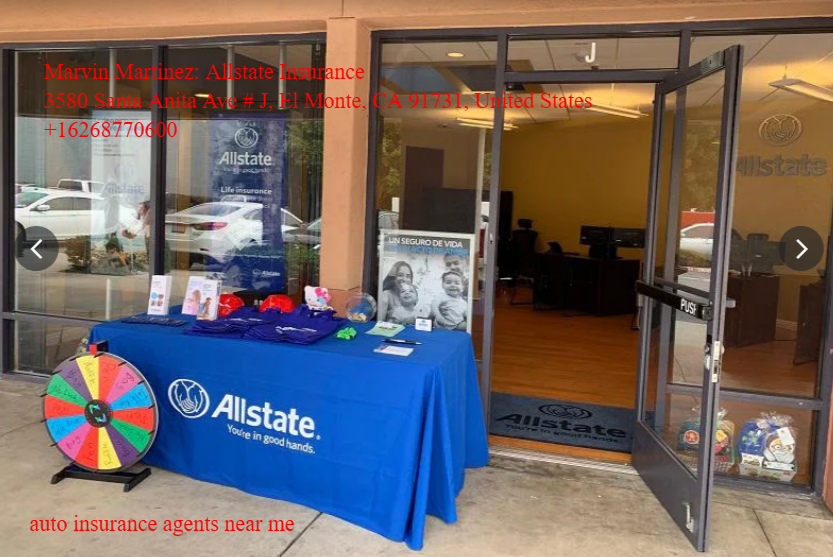
Local organisations might possibly be exceedingly successful whilst local context matters. A area near Lambert Park may perhaps have a diverse profile than one tucked into a quieter residential pocket near Arceo Park or towards the commercial corridors by Lower Azusa Road. Agencies with a mighty attractiveness in the town steadily recognize those neighborhood important points, and which can make the insurance communique extra simple and less standard. If you might be comparing suggestions, you'll be able to stumble upon searches and thoughts tied to allstate insurance coverage, prime-rated regional workplaces, or terms like marvin martinez: allstate assurance professional training, marvin martinez: allstate assurance pretty rated, and marvin martinez: allstate coverage robust repute. What issues maximum is whether or not the employer listens rigorously, explains alternate-offs sincerely, and facilitates you construct protection round the house you literally offered.
The add-ons that remember extra than individuals think
Insurance endorsements are the place a decent coverage will become a nicely-fitted one. For first-time owners, those non-obligatory extras occasionally sound user-friendly to skip. Some are. Some are usually not.
Water backup insurance policy is one of many maximum helpful examples. Standard abode coverage as a rule does not fully defend in opposition t water backing up by means of drains or a sump machine. Even a small backup can harm floor, drywall, and stored objects instant. Another helpful choice is prolonged or elevated dwelling insurance, which could assistance if rebuilding prices jump after a sought after disaster. Scheduled non-public assets policy cover could make sense in the event you own an engagement ring, excessive-end digital camera gear, musical devices, or watches whose worth exceeds normal limits.
A more recent option valued at asking approximately is device breakdown policy, which might also assistance with sudden mechanical or electric failure regarding home methods and appliances. Service line policy cover can also be worthwhile, particularly for older residences wherein underground software traces should not whatever a shopper thinks about at some stage in escrow however would transform very genuine later.
There isn't any prize for having the fewest endorsements. The function is to dodge procuring things you do now not desire whereas covering in opposition t losses that might easily harm.
If you also want lifestyles coverage, prevent the communication separate satisfactory to assume clearly
First-time owners most of the time start considering severely about life insurance coverage round the identical time they buy a apartment. That makes sense. A mortgage ameliorations the stakes for anybody with a partner, toddlers, or family members members who depend upon their sales.
Still, it is helping to factor in home insurance coverage and lifestyles insurance plan as linked however dissimilar decisions. Home insurance coverage protects assets and legal responsibility. Life coverage protects the folks who would face economic difficulty whenever you died by surprise. Sometimes one agency can deal with either, and that convenience may also be invaluable. If you're already finding lifestyles assurance brokers close me or asking approximately existence insurance plan even though finalizing your householders policy, be sure that every one product still gets a correct evaluation on its possess terms.
The identical is precise in the event that your relatives is bundling multiple desires, including homestead coverage, automobile insurance coverage, and life coverage. There is also authentic reductions and ease in having one point of contact. But in no way let convenience update clarity. A visitor-targeted agent may want to find a way to walk via each one coverage separately, clarify what is covered, and tutor in which the mark downs come from.
What to have well prepared in the past you ask for quotes
The smoother your quote course of, the stronger your outcomes are usually. Not considering the fact that pace concerns, yet since accuracy does. If you're able to provide total data from the soar, you're less most probably to get a low quote that later ameliorations as soon as underwriting studies the estate.
Here is the fast variant of what more often than not helps:
- The property cope with, year outfitted, square pictures, and main points on roof, plumbing, electric, and HVAC updates Information about safety contraptions, smoke alarms, water leak detection, and any latest renovations A hard estimate of the fee of your belongings, extraordinarily prime-importance items Your favourite deductible wide variety and whether you want to package with car insurance Any questions on renting a room, working from residence, pets, or detailed platforms at the property
That last object topics since domicile use is exchanging. Many men and women paintings remotely, run aspect organisations, or host family unit for accelerated intervals. If you might be storing work gadget, seeing buyers at domicile, or incomes source of revenue from a component to the estate, say so up the front. It is an awful lot more uncomplicated to tailor protection now than to argue approximately motive after a claim.
Common error first-time owners make
The largest mistake is purchasing elegant on premium alone. The second largest is assuming the mortgage employer’s insurance requirement is sufficient to look after you. Lenders care that the collateral is insured. They should not evaluating regardless of whether your non-public estate limit makes sense, even if your liability policy is strong, or whether or not your deductible is reasonable.
Another widely used mistake is forgetting to replace the policy after movement-in. People redecorate kitchens, upload outdoor platforms, change outdated approaches, buy more desirable furniture, or delivery applying component to the home for business recreation. The coverage may still evolve with the belongings. If it does no longer, you can actually find that your “dependable” insurance plan slowly turned into superseded without understanding it.
I actually have also seen people today underestimate the significance of stock. After a tremendous loss, remembering each and every shirt, appliance, instrument, pan, lamp, and equipment in the space is tougher than it sounds. Keep photographs. Save receipts for significant items wherein you're able to. A sensible room-through-room video for your mobilephone once or twice a yr could make claims simpler later.
How region inside of El Monte can shape the conversation
El Monte seriously isn't one-measurement-fits-all from an insurance point of view. Homes close busier corridors round Garvey Avenue or Valley Boulevard may possibly improve specific questions than houses in quieter inner tracts. Properties close the Whittier Narrows place may instantaneous extra discussion round water publicity and drainage historical past. Older homes around common neighborhoods can convey repairs and formula-age worries that more moderen people today have not dealt with previously. If your vicinity sits near great commuter routes just like the 10 or the 605, site visitors patterns and regional density will even enter the image in tactics that aren't apparent until an insurer begins asking questions.
Landmarks guide localize the communication too. A house no longer a long way from the El Monte Historical Museum might also replicate older development tendencies. A belongings close the Santa Fe Trail enviornment can also have web page-definite traits that count for underwriting. Even nearby civic and park spaces, like Zamora Park or the neighborhoods surrounding El Monte High School, can guide an experienced neighborhood place of business suppose by way of life like publicity, response occasions, and rebuilding realities.
That is where a good organisation with professional integrity is additionally very good. People generally seek vast terms like car or truck insurance coverage marketers, car insurance plan agent, automobile coverage agent close to me, or insurance retailers near me while what they really want is individual who is aware the neighborhood housing inventory and will clarify why one endorsement subjects on one boulevard but not necessarily on one other.
Choosing an agent with out getting overwhelmed
A incredible assurance experience many times comes down to 2 issues: the first-rate of the coverage and the quality of the advice behind it. The most cost-effective quote can look engaging, yet if the explanations are rushed or vague, that is a warning signal. First-time home owners gain from sufferer practise. You should experience secure asking what sounds like a basic question and getting a straight answer in simple language.
Look for indicators of secure service. Does the place of business return calls? Do they explain substitute charge as opposed to really funds fee truly? Can they evaluate deductibles in actual buck phrases? Do they ask approximately your house, or do they just promote from a script? Those are more suitable alerts than advertising and marketing language by myself.
You may also see corporations defined as accurate-rated, 5-big name rated, devoted to excellence, or typical for bendy policy cover strategies. Those terms are effective as a place to begin, yet they mean more while subsidized by an sincere conversation. If a neighborhood administrative center resembling Marvin Martinez: Allstate Insurance in El Monte takes the time to explain what you might be shopping, how a declare would paintings, and where your best negative aspects in actuality are, that may be the form of magnitude first-time property owners tend to count number.
A plain method to choose regardless of whether a policy is probably precise for you
After you review prices, step lower back and ask yourself three simple questions.
First, if the condominium have been badly broken, does the house insurance policy consider realistic for rebuilding? Second, in the event you needed to substitute most of your belongings, might the private estate decrease get you shut? Third, if any individual had been significantly injured on your property, would your liability protection suppose adequate?
If you hesitate on any of these, retain asking questions. This is one purchase where a bit excess patience can retailer plenty of stress later.
First residences include sufficient surprises already. Your assurance deserve to now not be one in every of them. A forged owners coverage, equipped with clean coaching and functional limits, provides you room to relish the condominium you labored so difficult to purchase, whether or not that space sits close Lambert Park, in the direction of Mountain View, or in considered one of El Monte’s quiet residential streets wherein the correct days are aas a rule the elementary ones.